

You can get access to our charts and data inside our TBL Pulse Dashboard:

Dear Readers,
Another summer week is done…where has 2026 gone? It’s almost September!
As I wrote in a letter two weeks ago, with both tax season and the World Cup coming to an end, I have been cautiously bullish on the US economy. With a diminishing savings rate, tax refunds out of the way, and the World Cup retail sales pump fading, there are fewer consumer spending sources during the second half of 2026. This has had me fading the bearish narrative currently plaguing US Treasuries.
Sentiment out there is placing too much emphasis on inflation…almost forgetting that labor is not necessarily shining. I will copy what I said on August 1st:
The Fed is already tightening
Not only is the labor market showing signs of cooling, but the Fed is technically tightening despite maintaining its policy rate unchanged. Have a look at the San Francisco Fed’s “Proxy Fed Funds Rate,” something I discussed inside our TBL Pulse Community this week:
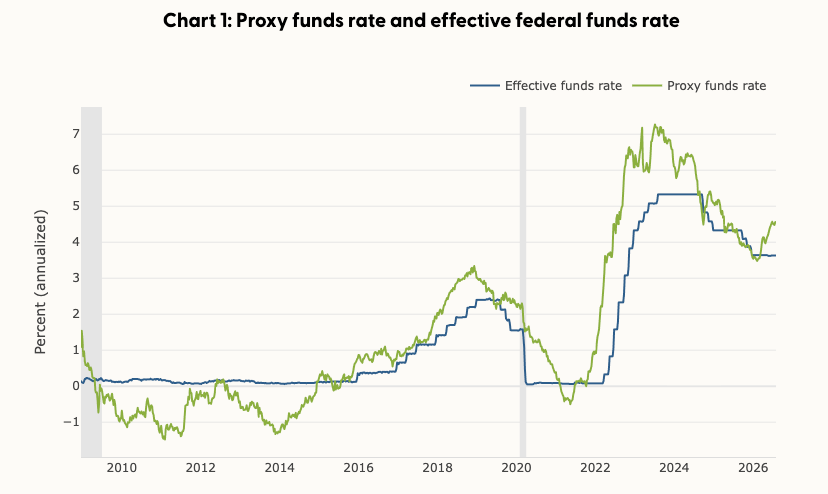
As the Fed writes, “[t]he proxy rate uses financial market data to infer the broad stance of monetary policy as determined by funds rate changes, forward guidance about projected future rates, and balance sheet changes.” And although forward guidance is out the window now, balance sheet conditions are still baked into the proxy.
SOMA Tightening
The US Treasury’s most recent QRA statement reiterated that it is monitoring T-bill SOMA purchases as a source of demand for issuance at the very short end of the curve. This is arguably one of the main culprits for the proxy Fed funds rate appearing higher than the current policy rate (chart above). Not because it is buying T-bills, but because of what it’s trading for them. That’s where the tightening is happening, really.
As the Fed reinvests long-term assets (think MBS) into the short-end of the curve (T-bills), you see SOMA’s weighted-average maturity fall (chart below):
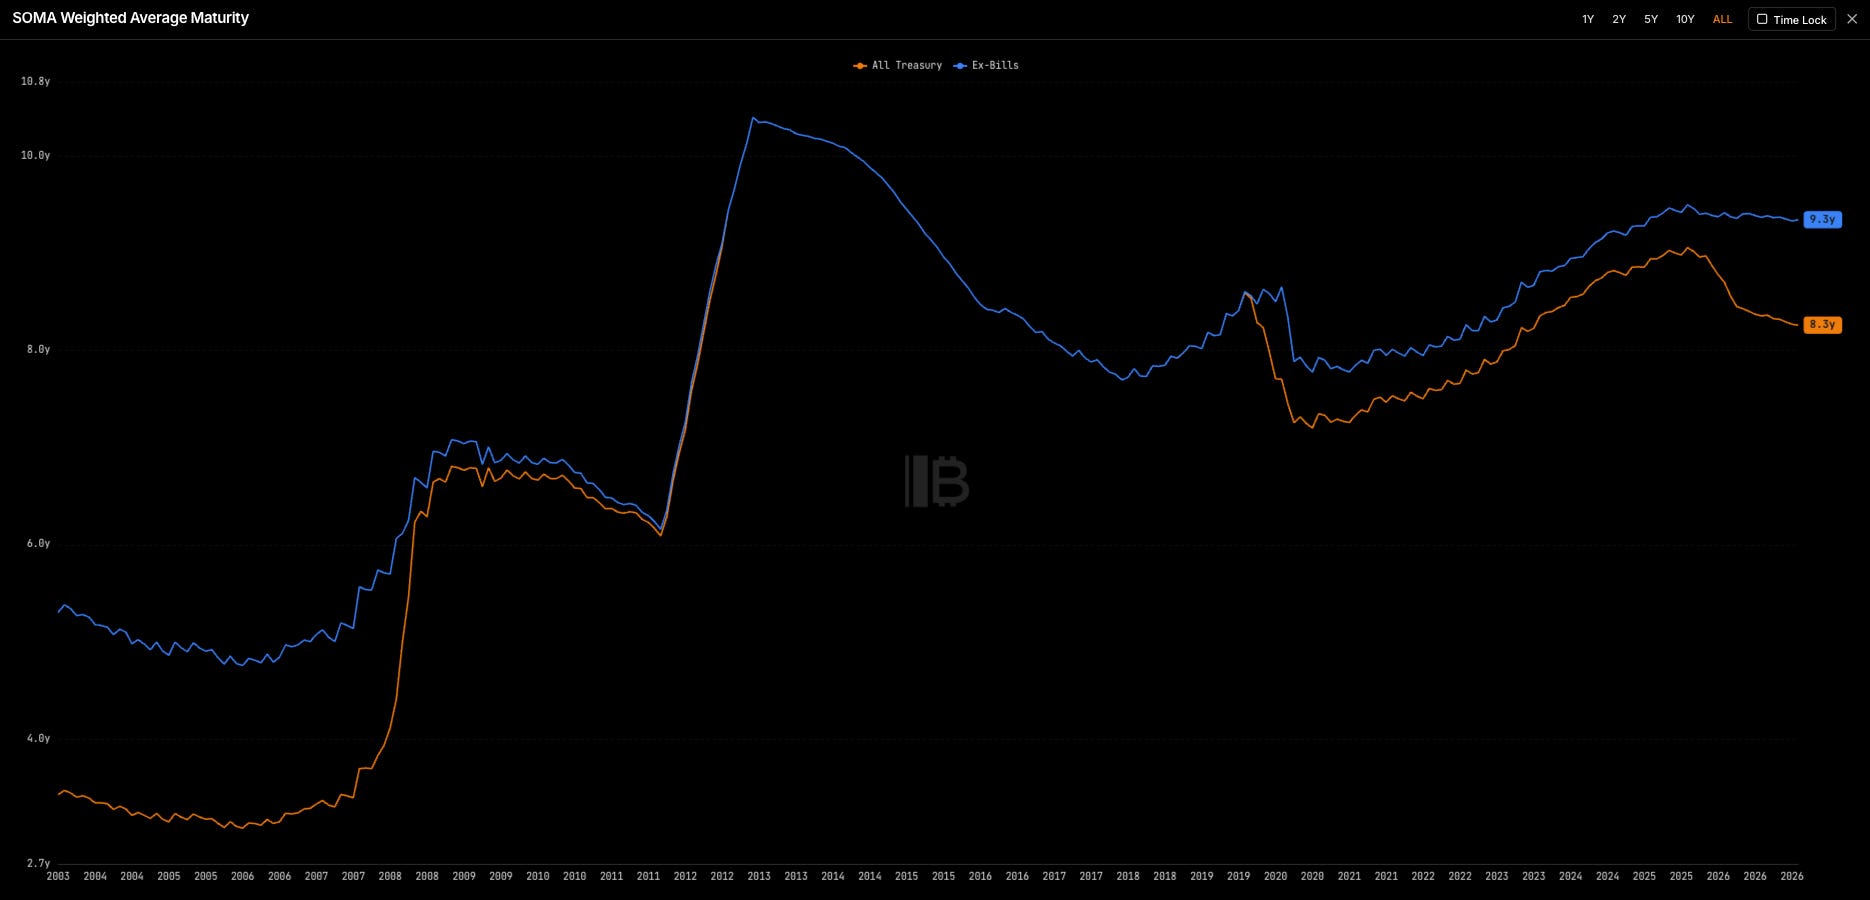
This is something the Fed has wanted to do for a while now…more on this shortly. For now, suffice it to say that, as the Fed transitions into shorter-term securities, its thumb on the scale of duration risk is less heavy.
It is effectively leaving the private market to absorb any duration on its own (a.k.a., a form of tightening). As Warsh put it in his most recent meeting, the market is doing his tightening for him.
A short sidequest here: Why does the Fed want SOMA WAM down?
There are many reasons for wanting to bring WAM down, and Fed watchers will either agree or disagree with me here. But my take narrows it down to a couple reasons. Malleability (or market neutrality) and operating losses.
A malleable balance sheet: Shorter-term assets make the Fed’s balance sheet a lot more flexible. It could allow it to enter duration (think large-scale asset purchases) without massively altering the size of the balance sheet, since T-bills mature faster and provide a source of cash without ‘printing.’ Shorter-term assets can also allow it to reduce the size of its balance sheet without impacting market duration. The goal is ultimately to become more market neutral.
Operating losses: Simply, when the Fed is paying a higher interest on reserves than it gets from its long-, low-yielding Treasuries (that it bought back in 2020, for example), it is losing. T-bills adjust upward with IORB.
Anyway, back to the article…
The US Economy
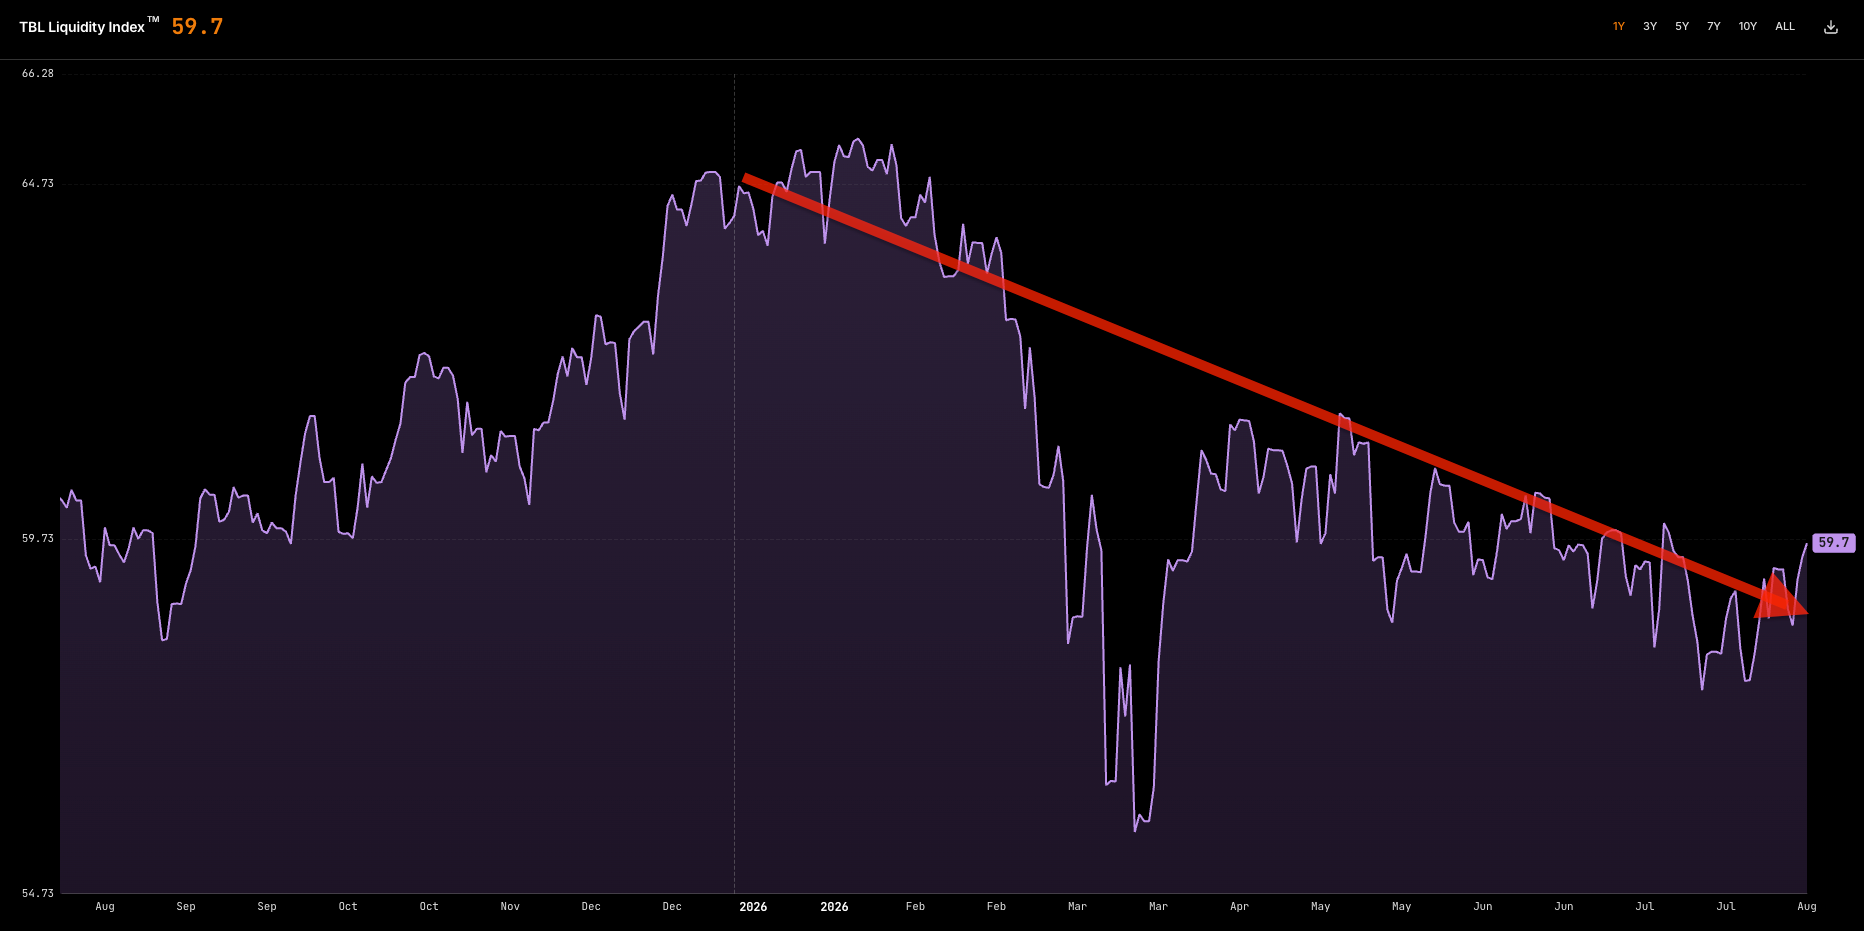
To summarize, the Fed is tighter than most think. Even our own TBL Liquidity Index has experienced a slowdown this year (albeit still in the expansionary territory of above 50 and showing signs of improvement):
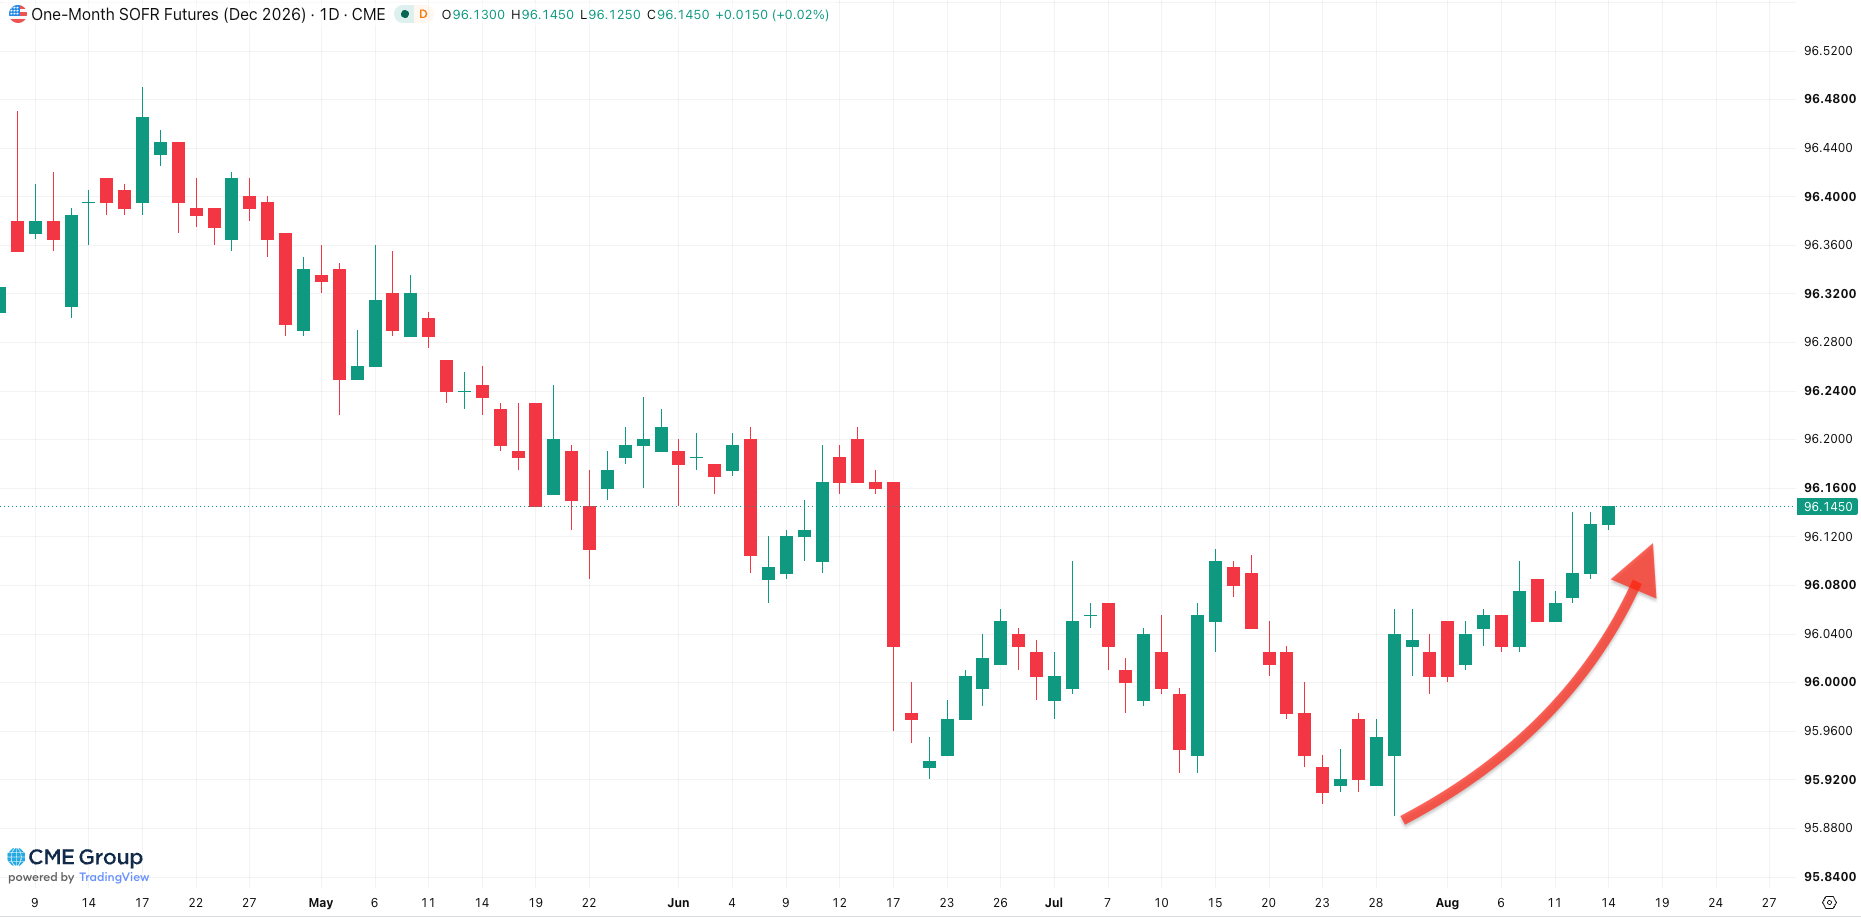
The market is coming to terms with these existing tighter conditions. After this week’s highly anticipated CPI print, the results of which were largely benign (at expectations), the market started to take its foot off the ‘hiking’ pedal. Then PPI’s cooler-than-expected print came in as a double-whammy. December 2026 one-month SOFR futures surged this week, implying lower hiking expectations by EOY:
If you want the US economy to continue Rock-and-Rolling, hikes are probably not the move. You need a continuation of the consumer spending boosts that we saw during 1H26.
Retail sales on Friday continued to build on this idea that 2H26 will be a lot slower for the consumer. The results for July were MUCH cooler than expected. The control group (which is baked into GDP calculations) missed big, coming in at -0.4% versus the expected +0.3% MoM:
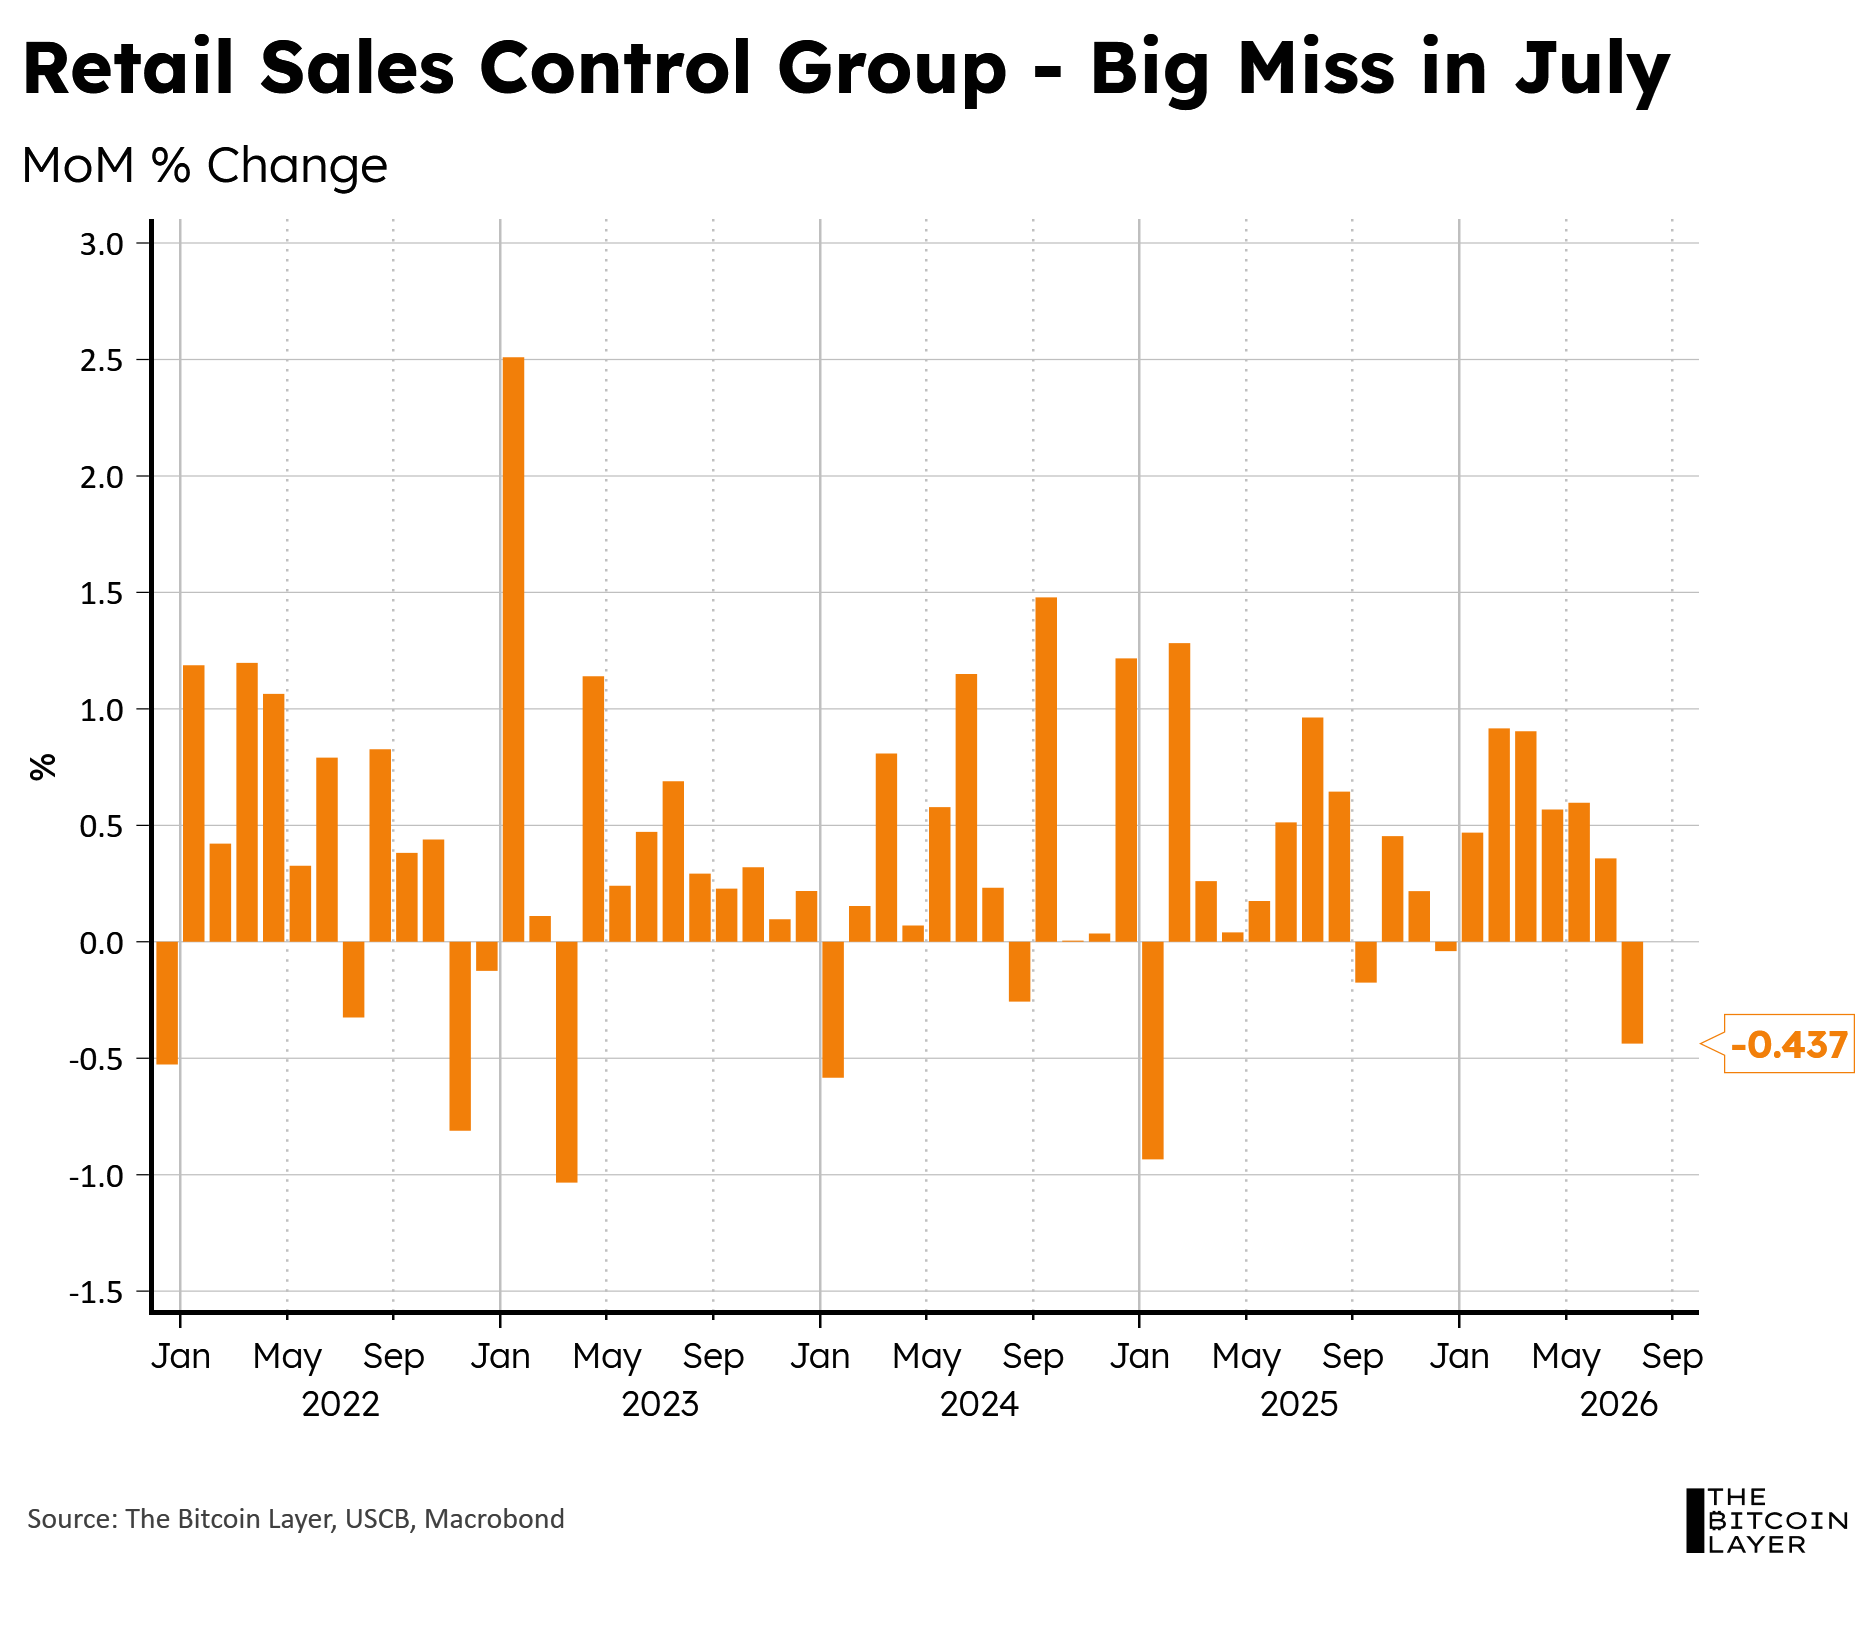
There’s a lot of seasonality in these numbers, of course. The Bank of America expected these lower numbers for similar reasons that we did: post-World-Cup effects.
So, the question is: where’s the next boost to consumption coming from? For now, I place my bets on risk assets. The stock market could “self-fulfillingly” be that very source of strength the consumer needs…
Risk Is Not Really Feeling the Slowdown
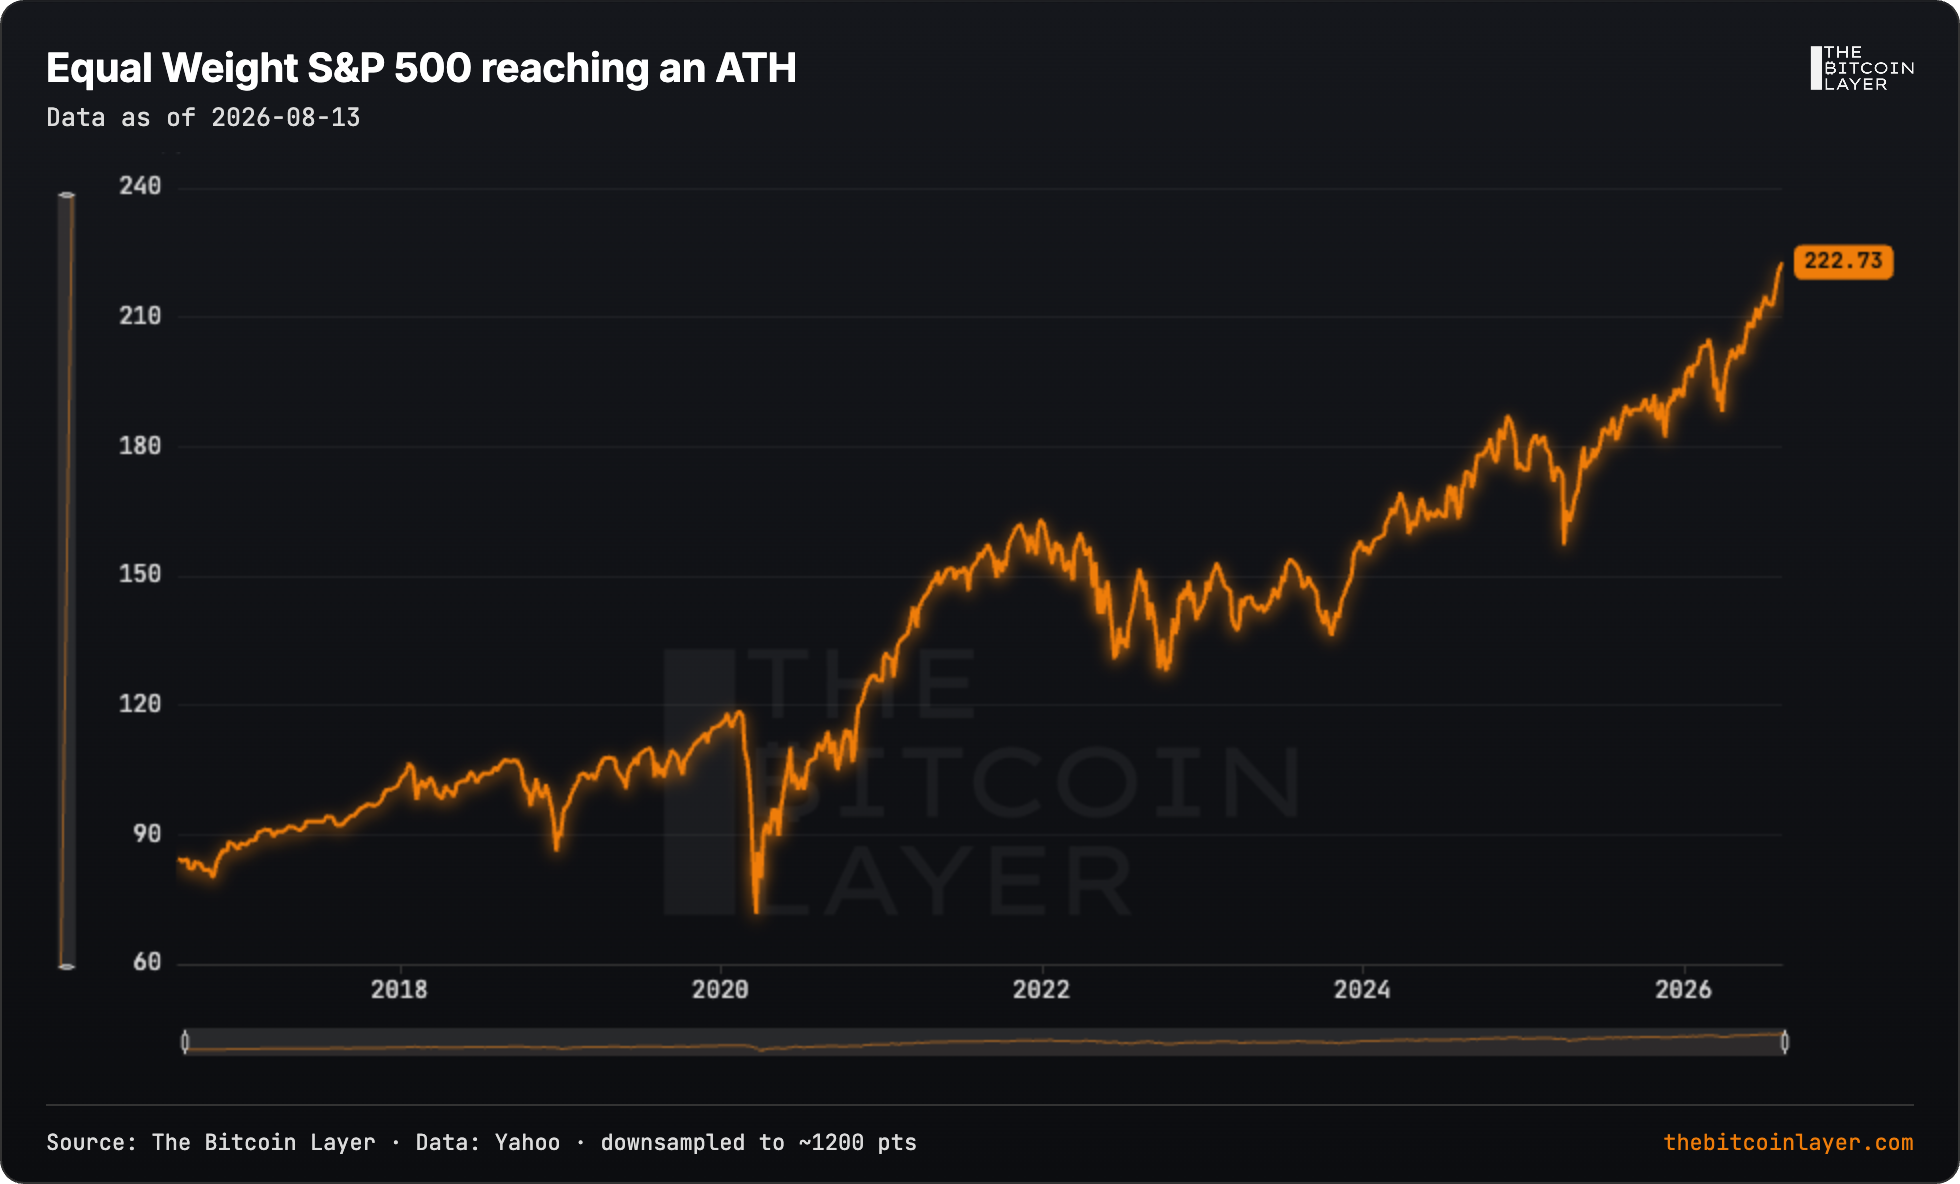
Despite the labor market slowing (which is a headwind for consumption), we also see a lot more market breadth. The equal-weight S&P 500 made a new ATH this week:
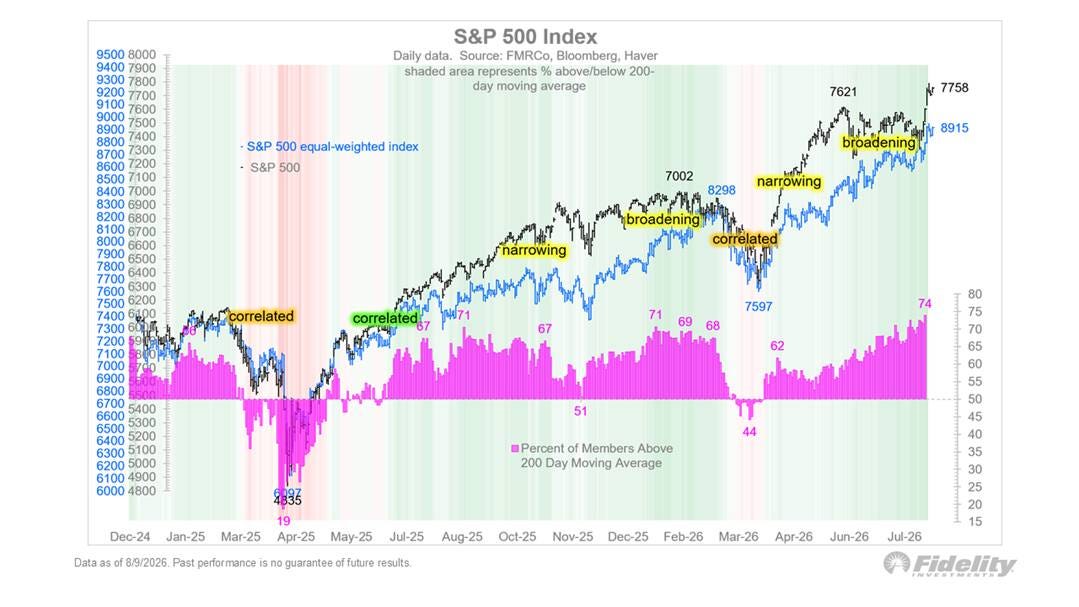
To paraphrase Fidelity, during the last rally in 1999, only 20% of stocks were above their 200-day moving average. Today, that figure is approximately 74% (chart below):
Moreover, Q2’s earnings surpassed expectations. As Bloomberg puts it:
Overall, 85.2% of companies exceeded Wall Street’s EPS expectations through Monday’s close, which is the highest percentage since 2021[...].
There is market breadth, so don’t sleep on the wealth effect to carry the US consumption picture.
The wealth effect, or just very good marketing from movie producers. Have a look at box office grosses lately:
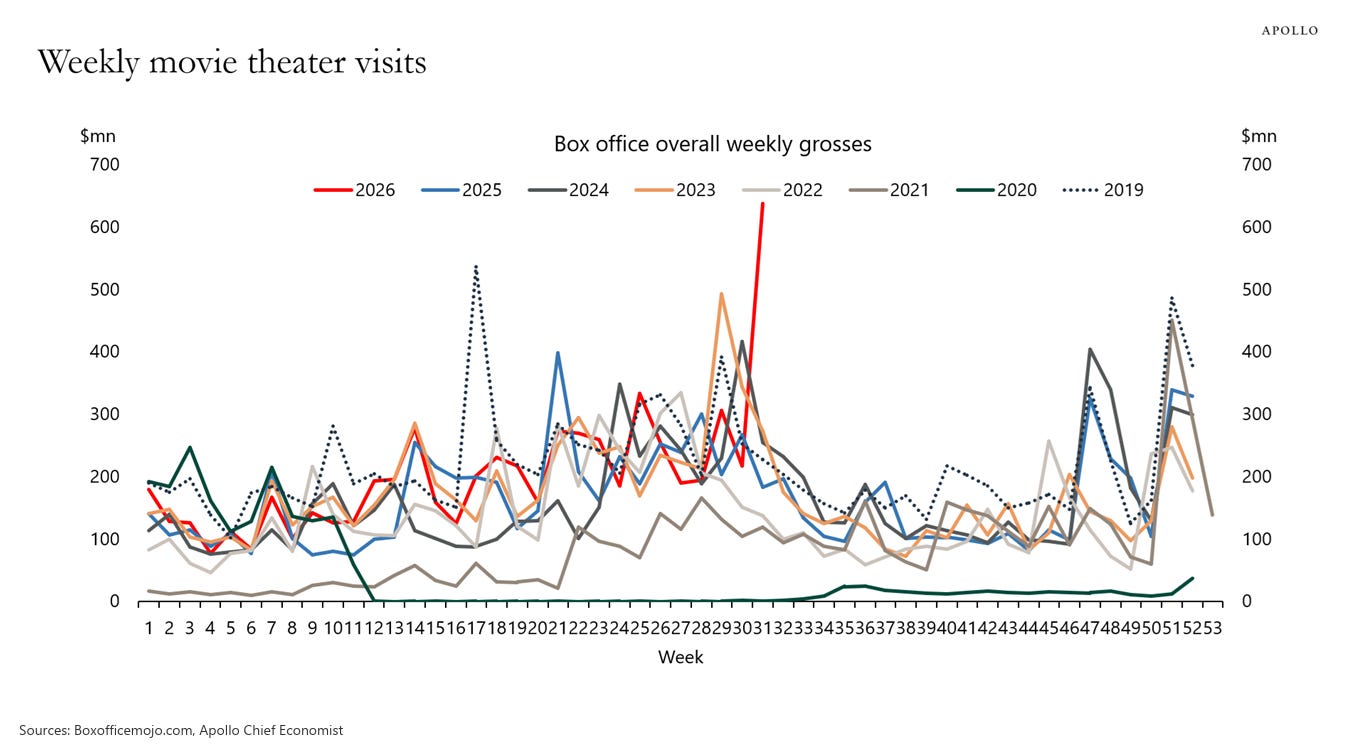
I already watched The Odyssey (6.5/10, in my humble opinion), and will be watching Spider-Man this weekend.
Anyway, in all seriousness, what I am trying to say is the consumer has clearly not gone anywhere; I simply need to see some more economic tailwinds. This is why I say I am cautiously bullish on the US economy…and why I understand some US rates traders placing short butterfly trades on the curve (going long 2s and 30s, and short 10s). Bullish 2s because the hiking story is overdone, bullish 30s because the back-end could be in dip-buying territory, but hedging against a strong US economy by shorting 10s.
The AI Race
As the East versus West AI race continues, we are seeing declines in the LLM Token Expenditure Index, which, as Silicon Data puts it, tells you how much the AI market is paying for a million LLM tokens (regardless of the model). This past week, the model declined nearly 10%:
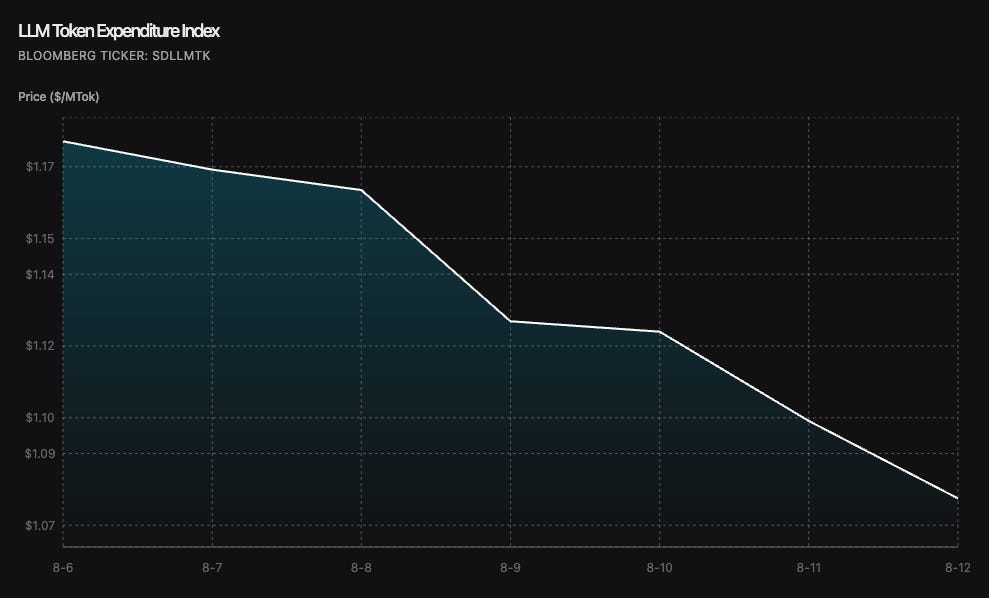
Some narratives out there argue that this recent decline in price could be ascribed to Chinese models (like Kimi from Moonshot AI) competing with American models.
We unfortunately don’t have full access to this Silicon Data index, but if any of you do, please post it in our Community. I, for one, would love to see the overall trend over the past few months at least.
Either way, there’s clear competition for end-use market share in AI, which is beneficial for consumers like us, who end up paying less for tokens. However, I don’t know about you guys, but my computer has been barely keeping up with the amount of stuff I need it to do now that I am using Claude Code daily.
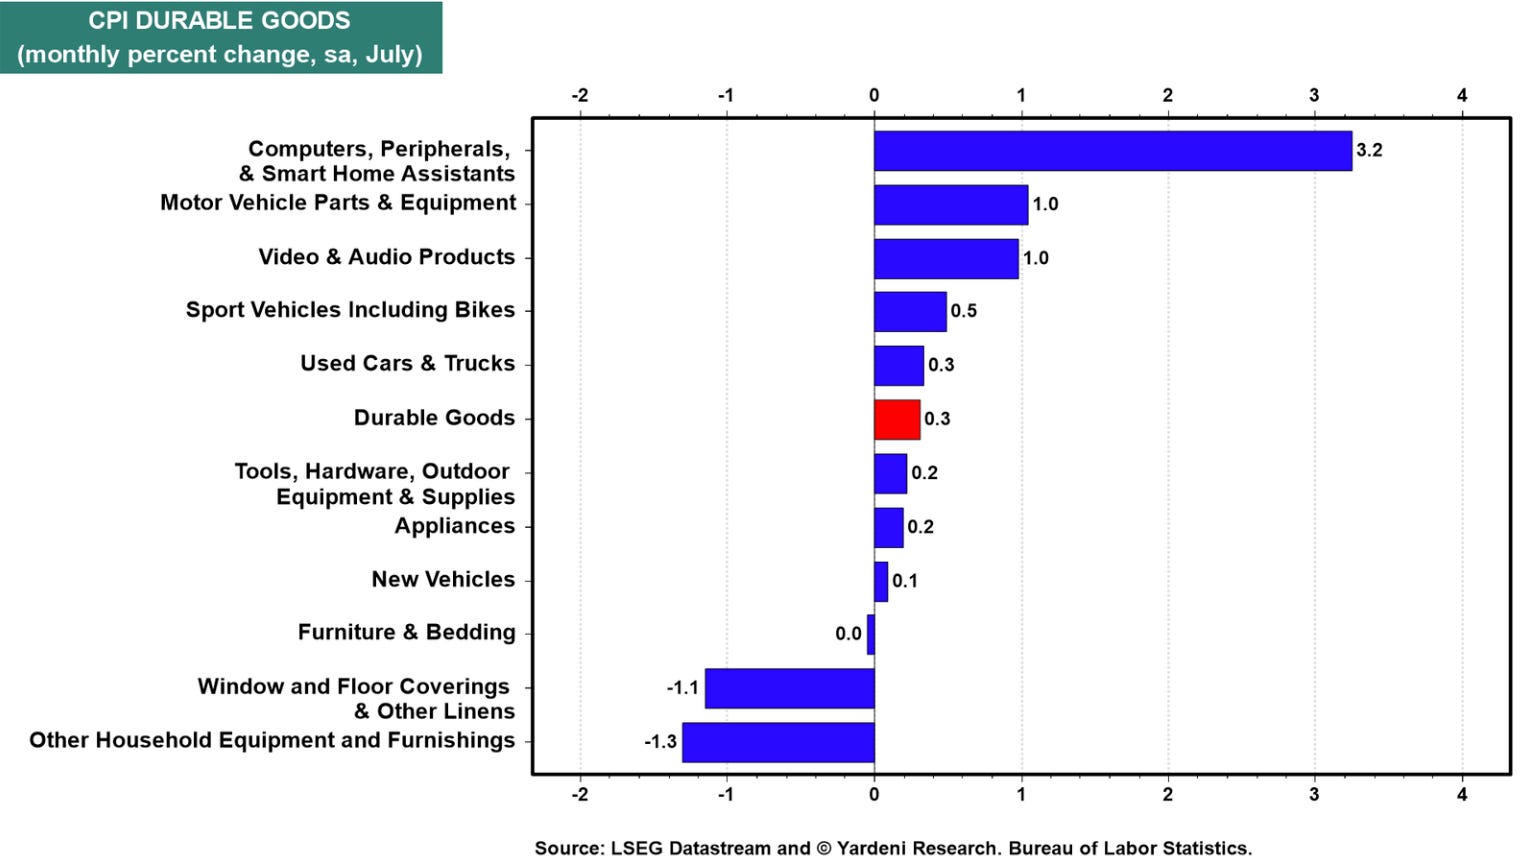
Cheap tokens are great and all, but as the price of tokens decreases, usage could inversely increase, which leads to users demanding new and better hardware. July’s CPI print showed us that computer prices surged on a monthly basis:
We even saw Intel offer equity this week for the first time in 55 years to capitalize on this AI boom…which wasn’t great for our SOXX ETF inside our Model Portfolio at the start of the week, but Intel ended up recovering from those dilution fears.
All this to say, I am not blind to the fact that AI inflation pressures remain. What I am watching is whether the consumer has the funds to keep up with rising prices and consumption overall, and if they don’t, then higher interest rates can really harm this AI-led economy.
Substack This Week
Nik’s letter went out on Monday; and
Johan’s weekly letter went out on Wednesday.


YouTube This Week
This week Demian brought back a very special guest for TBL, Joe Consorti, to discuss the Clarity Act:
For Podcast Listeners
Here are the links to our latest episode:
SPOTIFY
APPLE

Our videos are on major podcast platforms—take us with you on the go!
Apple Podcasts Spotify
Keep up with The Bitcoin Layer by following our social media!
YouTube X LinkedIn
Disclaimer
The TBL Model Portfolio, TBL Liquidity Indicator, and all TBL research outputs reflect Nik Bhatia and team’s analytical positioning for the macro and bitcoin environment. They are published for educational purposes only and are not investment advice, not a solicitation to buy or sell securities, and not a recommendation tailored to any individual’s portfolio. The Bitcoin Layer is not a registered investment advisor and does not manage client money. Please consult a professional financial advisor and conduct independent due diligence before making investment decisions.